Delta Air Lines enters Monday facing two very different shocks, with a weekend flight diversion drawing public attention just as another rise in oil threatens to put renewed pressure on airline earnings.
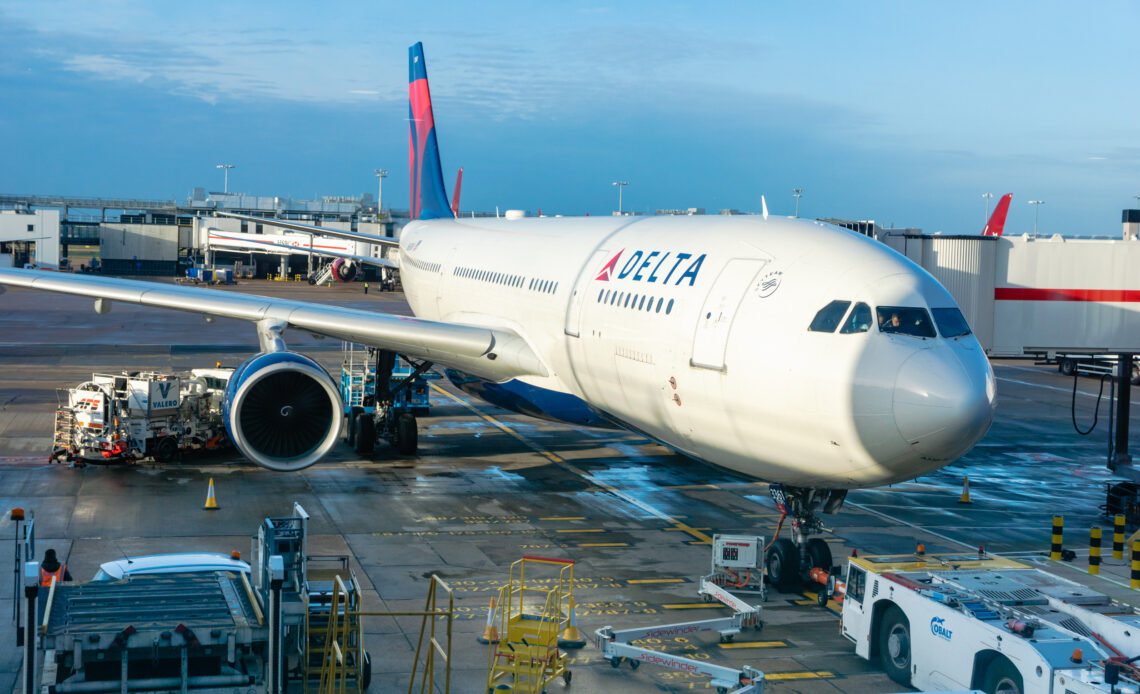
Flight DL251 from Barcelona to Boston diverted to Porto on Sunday after smoke was reported in the cabin. Delta said the Airbus A330 experienced a mechanical issue and landed safely.
Eight passengers were treated on the tarmac and three others were taken to hospital.
Yet for investors, the bigger financial problem may be Brent crude, which climbed above $106 a barrel on Monday after Delta shares finished Friday 2.63% higher at $84.94.
The visible shock is not necessarily the costly one
The DL251 incident creates an immediate operational and reputational headline, but there is no evidence yet that it will have a material effect on Delta’s finances.
Fuel costs have a much clearer route into the income statement.
Delta’s September-quarter guidance assumes an all-in fuel price of about $3.15 a gallon, including a refinery benefit, alongside an operating margin of 11% to 13% and earnings of $2.00 to $2.50 a share.
Brent’s return above $106 therefore matters because sustained crude strength can quickly raise the cost base underlying those forecasts. That reverses some of last week’s relief.
The distinction is important, as one weekend event may dominate searches and social media, while the other can force analysts to revise earnings models across several quarters.
Wall Street was already cutting estimates
UBS analysts Atul Maheswari and Thomas Wadewitz warned last week that higher fuel prices were already forcing changes to airline forecasts, despite resilient travel demand.
“We see meaningful downside to the implied fourth-quarter earnings per share outlooks and 2027 estimates given the forward curve for fuel currently,” the analysts said in a note.
UBS nevertheless described Delta as its top airline pick heading into earnings, highlighting the contradiction now shaping the stock.
Pricing and demand remain strong, but fuel is absorbing more of that revenue strength before it reaches the bottom line.
The bank said airlines had achieved larger fare increases than expected with limited consumer pushback, but also cut near-term earnings estimates across most of the sector. That makes fuel the variable most capable of spoiling an otherwise improving setup.
That warning becomes more relevant if Brent remains around current levels. Delta may need stronger fares and premium revenue simply to defend the margins investors had already expected.
Premium demand is Delta’s main defence
The bull case has not disappeared. Rothschild & Co Redburn analyst James Goodall said earlier this month that “international operations” remained a bright spot for US network carriers, helped by resilient demand and modest capacity growth across the North Atlantic.
Redburn kept a Buy rating on Delta and a $105 price target even after raising its jet-fuel forecasts, arguing that premium demand, constrained capacity and weaker low-cost competition should continue supporting unit revenue.
Barclays has made a similar argument while acknowledging the energy problem.
The bank cut its Delta target to $95 from $105 but retained an Overweight rating, saying stronger revenue could create structurally higher margins if energy markets eventually return to prewar levels.
That leaves Delta with a cleaner investment debate than the weekend headlines suggest. The next few sessions should show which risk investors are actually pricing.
The airline’s revenue engine is still working, but oil is deciding how much of that strength shareholders get to keep.
The post Delta stock enters Monday with two shocks: investors may be watching the wrong one appeared first on Invezz