The story everyone got wrong this week is that Amazon blocking Meta’s Muse AI agent was a setback for Meta. It was not. Between the agent’s launch on 8 September and the close on 24 September, Meta stock rose from $613.48 to $777.59, a 26.8% move worth roughly $416bn of market capitalisation on Nasdaq’s $1.973trn valuation. Over the same stretch, the four listed companies most often named as agentic-commerce casualties — Charles Schwab, LPL Financial, Booking Holdings and Expedia — shed about $35bn between them. That is the number that matters, and it points the opposite way from the consensus: the market is not pricing AI agents as a transfer of value from incumbents to Meta. It is pricing them as creation, at roughly twelve dollars made for every one destroyed.
Having watched the bank-versus-aggregator fight play out over six years — JPMorgan and Wells Fargo throttling Plaid and Yodlee, the screen-scraping bans, the inevitable capitulation into paid APIs and a rulemaking — the Amazon–Meta standoff reads like a rerun with better graphics. Amazon is the bank. Muse is the aggregator. The terms-of-service language is nearly identical, the commercial logic is identical, and the ending is almost certainly identical too: not a permanent block, but a metered, priced, rate-limited agent lane. The difference is that this time the repricing hit brokerage and travel equities before anyone wrote the rule.
The insight: this is a shelf-space fight, not a technology fight
Muse can book appointments and travel, fill in electronic forms, monitor home security cameras, and shop across sites and marketplaces, linking to Shopify or Stripe for payment. None of that is technically novel. What is novel is that a company with roughly three billion daily users has put an agent with payment rails in front of them and made it the number one free app on Apple’s US App Store, ahead of ChatGPT, inside two weeks. Distribution, not model quality, is the asset.
Amazon’s response was to refuse. It blocked Muse from buying products on its site, arguing the behaviour violates its terms of service. In a statement to CNBC, Amazon said that “third-party applications that offer to make purchases on behalf of customers from other businesses should operate openly and respect service provider decisions about whether or not to participate.” That sentence is the entire dispute in miniature, and Matthew Hassett, chief executive of smart alarm clock maker Loftie and of AI commerce startup Deliberate, translated it with unusual precision: Amazon’s “whole model is fiercely guarding the customer relationship,” he said, and “‘Respect service provider decisions’ is the polite version of ‘not on our shelf.'”
This is not Amazon’s first refusal. It sued Perplexity in November, alleging the startup concealed its agents to keep scraping the retailer’s site without approval, and it has blocked agentic tools from OpenAI and Google. A pattern of three is a policy. For anyone running a brokerage, an exchange, a payments business or a trading platform, the question stops being “will agents arrive” and becomes “on whose terms, at what price, and who writes the contract.”
Key facts: the Muse repricing, 8–24 September 2026
- Meta closed at $777.59 on 24 September, up 26.8% from $613.48 on 8 September — roughly $416bn of market value added on a $1.973trn cap — Nasdaq historical quotes, 24 Sep 2026
- The single biggest day was 21 September, +11.3% ($665.75 to $741.25), after Wells Fargo lifted its target to $796 from $640 — TipRanks, 21 Sep 2026
- Muse passed 2.5 million downloads and took the top free slot on the US App Store, displacing ChatGPT — CNN Business, 23 Sep 2026
- Charles Schwab fell 6.1% on 22 September and 6.9% over the period, to $99.49; LPL Financial fell 7.5% on 22 September and 13.6% over the period, to $302.76 — Nasdaq historical quotes
- Booking Holdings fell 5.1% on 23 September and 12.7% over the period, to $157.41; Expedia fell 7.7% on 23 September and 4.7% over the period, to $261.75 — Nasdaq historical quotes
- Combined market value of the four on 24 September: $344.9bn, implying roughly $35bn lost since Muse launched — FinanceFeeds calculation from Nasdaq market-cap and close data
- Meta hardware announced at Connect: the Muse Charm, $349 Ray-Ban Meta Audio glasses, and $1,299 Meta VR Glasses for spring 2027 — CNBC, 24 Sep 2026
What actually happened, and why the block matters more than the app
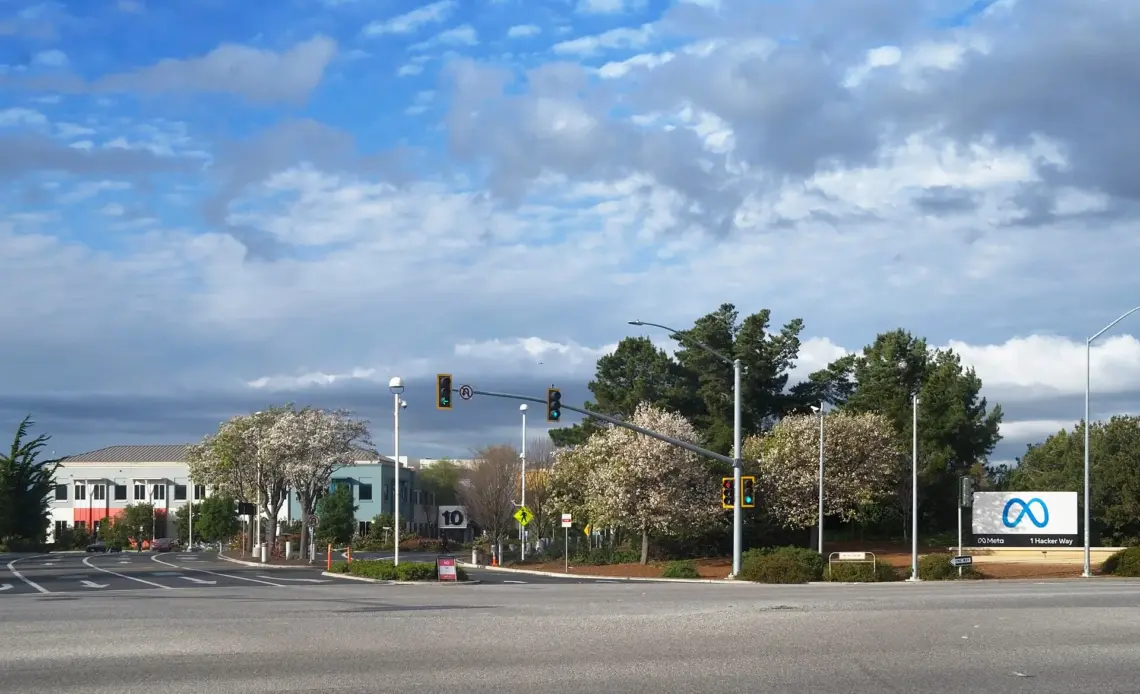
Mark Zuckerberg opened Meta Connect in Menlo Park on the evening of 23 September and described Muse as the centrepiece of the company’s effort to put AI in front of people who are not coders. “In the coming years, I expect that Muse is going to grow into the personal superintelligence that billions of people around the world are going to use to accomplish their goals and improve their lives,” he said.
Strip the rhetoric and there is a concrete claim underneath: Meta intends the agent to sit between the user and every transactional service they touch. That is the same position occupied, in different decades, by the retail branch, the travel agent, the introducing broker and the comparison site. Each of those layers was eventually squeezed by whoever controlled the point of intent. The reason Amazon reacted within days is that it understands the position precisely, having spent twenty-five years defending it.
Max Willens, an analyst at Emarketer, framed the stakes without hyperbole: “For many years, Amazon was the place most U.S. consumers went first if they wanted to buy something online. Today, those consumers are increasingly starting those shopper journeys with AI assistants.” A retailer that loses the first click loses the merchandising, the advertising inventory attached to it, and the data. Amazon’s advertising business is one of the most profitable things it does. An agent that answers “find me the cheapest one of these” without ever loading a sponsored listing is not a partner; it is a leak.
Not every retailer took Amazon’s view. Meta’s AI chief, Alexandr Wang, said at Connect that the company has enlisted Walmart, Best Buy, Gap, Sephora and Wayfair as Muse partners. “One of the great promises of e-commerce since the earliest days of the industry has been that it can save you money and time,” Wang said. “Personal agents are going to continue delivering on that promise for a new generation of shoppers.” The split is instructive. Merchants with a weaker direct relationship want the traffic. The one with the strongest direct relationship wants the wall. Payments has already picked a side: PayPal customers can now check out through Muse, which is exactly the kind of rail Amazon is refusing to become.
The financial-services read: why Schwab and LPL fell before Booking did
The sequencing in the tape is the most underreported detail of the week. Schwab and LPL Financial broke on Tuesday 22 September — down 6.1% and 7.5% respectively — a full session before Booking and Expedia broke on Wednesday. Retail brokerage repriced first, and it repriced harder in percentage terms at LPL than anything in travel.
That ordering makes sense if you read the product description rather than the headlines. Muse’s advertised capabilities include filling out electronic forms on a user’s behalf and executing multi-step tasks across a user’s connected accounts. Account opening, ACAT transfers, advisory onboarding and fund selection are form-filling problems wrapped in a distribution moat. LPL’s business in particular is the distribution moat: it is the plumbing that lets independent advisers run a practice. An agent that can compare, open and fund an account across providers attacks the switching cost that makes that plumbing valuable, and LPL’s smaller float means the repricing lands harder.
The incumbents are not standing still. Schwab has already put Anthropic’s Claude in front of more than 16,000 independent RIAs, which is the defensive move that works: own the agent inside your own walls rather than trying to keep somebody else’s agent out. Blocking is a losing strategy for a broker in a way it is not for a retailer, because a broker’s product is already digital, already API-shaped, and already regulated into interoperability. There is no shelf to keep Muse off.
Market impact and the data synthesis nobody is running
Here is the arithmetic that undercuts the disintermediation narrative. Using Nasdaq’s 24 September market caps and the 8 September closes, Schwab lost roughly $12.8bn of value, Booking roughly $17.3bn, LPL roughly $3.7bn and Expedia roughly $1.5bn — about $35bn in total. Meta added roughly $416bn.
If this were a pure zero-sum land grab, those numbers would be far closer together, and the disintermediation basket would be much wider than four names. It is not. The ratio is close to twelve to one, which tells you the market believes Muse creates a new consumption surface rather than merely diverting an existing one — and that the visible victims are being sold as a hedge, not as a thesis. That reading has an uncomfortable corollary for Meta bulls: a 26.8% re-rating on an unmonetised product is a valuation event, not an earnings event.
One quiet consequence of the re-rating is that the stock has already run past the sell-side. Wall Street’s average Meta price target stands at $763.67, against 38 Buy ratings, six Holds and no Sells, according to TipRanks — roughly 1.8% below the 24 September close. Wells Fargo’s Ken Gawrelski, who moved his target to $796 from $640 on 21 September, and Citi, which kept an $800 target while putting Meta on a 90-day catalyst watch into Connect, are now among the few whose numbers still sit above the tape. A consensus target beneath the price is not a sell signal, but it does mean the marginal buyer is no longer being handed a valuation argument.
Analysts are saying as much in print. Cantor, which recommends buying the stock, published a note on 22 September headlined “Meta is racing while AI is pacing,” and wrote: “We believe the unit economics of Muse are being subsidized in the early days, but we think META has several paths to a profitable freemium model.” Mizuho was more bullish on the narrative mechanics: “We expect Connect to move the Muse story from app adoption to platform creation.” Both are describing optionality, not cash flow.
| Position | The bull case | The bear case |
|---|---|---|
| Distribution | Three billion daily users, top free US app in under two weeks, hardware funnel via glasses and the Muse Charm | App-store rank is a download metric, not a retention metric; Meta has repeatedly launched consumer products that peaked at launch |
| Monetisation | Freemium paths, commerce take rate, and an ads business that already prices intent better than anyone | Cantor says unit economics are subsidised today; almost all Meta revenue is still advertising |
| Access | Walmart, Best Buy, Gap, Sephora, Wayfair and PayPal on board | Amazon blocked outright, having already blocked OpenAI and Google and sued Perplexity |
| Trust | Agent handles credentials, calendars and payments inside an existing Meta login | Meta agreed last month to pay up to $17bn to settle state claims over child mental-health harms; consumer trust is the binding constraint |
Joseph Turow, professor emeritus at the University of Pennsylvania and a long-standing researcher on digital privacy, put the trust problem plainly: “People are going to be very wary,” he said, predicting a split between early adopters and a broader population that will only extend the agent to companies it already trusts. Handing a social network the keys to your calendar, your inbox and your card is a different proposition from letting it rank your feed, and the $17bn settlement is fresh.
The regulatory tension: who owns the right to act on your behalf
There is currently no settled law on agent access, and that vacuum is precisely where the value sits. Amazon’s position rests on contract — its terms of service — and on the argument that an agent transacting on a customer’s behalf without disclosure is deceptive. Meta’s implicit position is that a user’s authority to shop is the user’s to delegate. Both are defensible, and neither has been tested at scale.
The closest precedent is financial. When account aggregators began pulling bank data on customers’ behalf, US banks blocked them on the same reasoning Amazon is using now, and the fight ran for years before the Consumer Financial Protection Bureau’s Section 1033 rulemaking forced a permissioned-API regime. Europe got there faster through PSD2. In both cases the incumbent lost the right to block outright and won the right to set the technical terms and, indirectly, the cost. Meanwhile the Digital Markets Act already obliges designated gatekeepers to permit interoperability in defined circumstances, and Amazon and Meta are both designated. That is the live regulatory seam, and it is European, not American.
The other tension is timing. Zuckerberg is pushing into agentic AI at a moment when Anthropic and OpenAI are publicly calling for a slower model-development cadence, and while both face litigation alleging real-world harm from their systems. An agent with payment authority and inbox access raises a harder supervisory question than a chatbot: when an agent buys the wrong thing, or moves money to the wrong place, liability has to land somewhere. No regulator has said where.
What happens next: three calls
One: Amazon monetises the lane rather than holding the wall, within twelve months. Amazon does not have a history of leaving a toll uncollected. Blocking preserves the customer relationship today but forfeits the ad inventory and the take rate on agentic demand tomorrow, and the aggregator precedent says the block ends in an API with a price list. Watch for a paid, disclosed agent programme with rate limits and mandatory branding — the same shape as its advertising and fulfilment businesses.
Two: the next leg of the trade hits payments economics, not retail. Muse routes checkout through Shopify or Stripe. If agents become the default front end, affiliate fees, referral commissions and interchange all get renegotiated by a counterparty with no legacy relationship to defend. The equities to watch are not Booking and Expedia; they are the intermediaries whose revenue is a percentage of a funnel that the agent is about to skip.
Three: brokers build rather than block, and the ones that block underperform. Schwab’s Claude deployment is the template. A broker cannot keep an agent out of a regulated, API-mandated, digitally delivered product, so the defensible position is to be the agent the client already has. Expect at least two more large retail brokerages to announce agent partnerships before year-end, and expect the market to reward the announcement more than the economics justify — the same way it has rewarded Meta.
The number to hold on to is not the 26.8%. It is the twelve-to-one. Until the gap between what Meta gained and what the incumbents lost narrows, the market is telling you this is a story about a new surface, not a stolen one. Should Muse’s retention numbers disappoint after the launch spike, that ratio compresses from the top, and it will compress fast. For the record on where the risk sits, our Meta bull and bear case and the full inventory of what Meta actually shipped at Connect are both worth reading alongside this. The agent trade has already dragged the CPU complex up 32% in three sessions, which is a reasonable indication of how far the second-order repricing can run.
FAQ
Why did Amazon block Meta’s Muse AI agent?
Amazon says third-party applications that buy on a customer’s behalf from other businesses “should operate openly and respect service provider decisions about whether or not to participate.” In practice, Amazon is protecting the direct customer relationship and the advertising inventory attached to it. It has taken the same position against OpenAI and Google agents, and sued Perplexity in November over concealed agent traffic.
How much did Meta stock rise after Muse launched?
Meta closed at $613.48 on 8 September and $777.59 on 24 September, a gain of 26.8%, or roughly $416bn of market capitalisation against Nasdaq’s $1.973trn valuation. The largest single session was 21 September, when the stock rose 11.3% after Wells Fargo raised its price target to $796 from $640.
Which stocks fell because of the Meta Muse AI agent?
Charles Schwab and LPL Financial fell 6.1% and 7.5% on 22 September; Booking Holdings and Expedia fell 5.1% and 7.7% on 23 September. Across the period from Muse’s launch, the four lost roughly $35bn in combined market value, against a combined 24 September capitalisation of $344.9bn.
What is agentic commerce and why does it matter to brokers?
Agentic commerce is transacting through an AI agent that acts on a user’s behalf rather than through a company’s own interface. It matters to brokers because account opening, transfers and product selection are form-driven processes that an agent can execute across providers, attacking the switching costs that underpin distribution-led business models. Schwab’s response has been to deploy its own agent to more than 16,000 independent RIAs rather than attempt to block external ones.
Is the Amazon block likely to hold?
History suggests not in its current form. The nearest analogue is banks blocking account aggregators, which ended in permissioned APIs under the CFPB’s Section 1033 rule in the US and PSD2 in Europe. Both Amazon and Meta are designated gatekeepers under the EU’s Digital Markets Act, which already contemplates interoperability obligations. The likeliest outcome is a priced, disclosed and rate-limited agent lane rather than an indefinite wall.
Is Muse profitable for Meta?
No. Cantor analysts wrote on 22 September that “the unit economics of Muse are being subsidized in the early days,” while arguing Meta has several paths to a profitable freemium model. Meta still generates almost all of its revenue from digital advertising, so the current re-rating reflects optionality rather than realised earnings.