The easy read of Monday’s news is that Vistra landed another data centre customer. It did not, at least not in any way that moves Vistra’s numbers. The 20-year, 207-megawatt supply deal with New Era Energy & Digital (NASDAQ: NUAI) is about 5% of the 3,809 MW Vistra already has under 20-year contracts with Amazon and Meta, and Vistra shares closed up just 0.08% on the day while New Era’s jumped 30.5%. What is new is the structure: once power flows, Vistra gets a 5% non-voting equity stake in the part of the data centre it powers, plus a right of first refusal over every future on-site power build. None of Vistra’s disclosed hyperscaler contracts gives it a slice of the customer’s asset, and here it takes one with a counterparty whose required credit support, up to $198.8 million, exceeds its entire balance sheet. That pairing, disclosed in New Era’s Form 8-K filed on 21 September 2026, is the real story, and it shows how Vistra now prices the risk of selling power to data centres that have not been built yet.
Look at it from the credit desk rather than the trading screen. Having covered Vistra’s contract announcements since the Comanche Peak deal with Amazon Web Services a year ago, I read this one as a lender reads a mezzanine loan: a fixed-price supply contract, collateralised by a $116 million letter of credit, with a 5% equity sweetener that only pays off if the project succeeds. Vistra is not betting on New Era; it is getting paid for the option that New Era works. If the data centre fills with tenants, Vistra owns a piece of it and holds first call on the next gigawatt of generation. If it does not, Vistra draws on the letter of credit and still owns a 1,180 MW gas plant in one of the cheapest power zones in its footprint. The downside is secured and the upside is free. That asymmetry, not the megawatts, is what makes this deal worth reading line by line.
Key facts: the Vistra–New Era deal
- 200–207 MW for 20 years from Vistra’s 1,180 MW gas-fired plant in Odessa, Texas, delivery expected Q3 2027 — New Era press release, 21 Sep 2026
- 5% of the fully diluted equity of the powered project company goes to Vistra once delivery starts — New Era 8-K, 21 Sep 2026
- $116m letter of credit due within 15 business days of signing, plus up to $82.8m more security by first delivery — New Era 8-K
- $69.8m cash and $174.7m total assets at New Era on 30 June 2026 — New Era 10-Q, 14 Aug 2026
- +30.5% NUAI ($5.86 to $7.65) versus +0.08% VST ($140.67 to $140.78), 18–21 Sep closes — Nasdaq
- -$3.10/MMBtu average Permian Basin gas price and $24.71/MWh ERCOT West Hub power in Q2 2026 — Vistra 10-Q, 10 Aug 2026
- 474 GW of large-load requests in the ERCOT queue, about 90% from data centres — Houston Public Media, 3 Aug 2026
What Vistra Actually Signed, and Why the Equity Kicker Matters
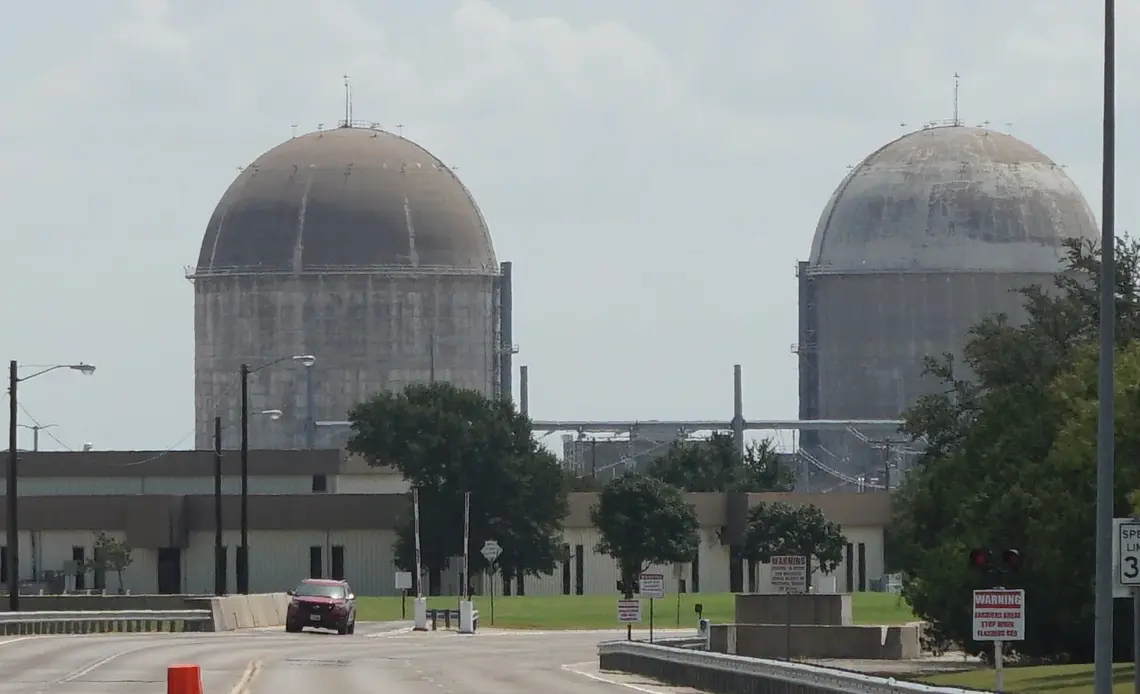
The contract has two parts. The first is a power purchase agreement between Luminant ET Services, Vistra’s trading affiliate, and TCDC PowerCo, a New Era subsidiary. Luminant will supply a minimum of 200 MW and up to 207 MW generated at the 1,180 MW Odessa plant owned by Vistra Operations Company, “or otherwise sourced from other available sources or the ERCOT grid”, to New Era’s Texas Critical Data Center on land next to the plant. The initial term is 20 years from first delivery, with automatic one-year renewals. Luminant’s obligations depend on conditions precedent being met by 31 December 2027, including a purchase agreement for the substation and related equipment.
The second part is a development framework agreement, signed alongside the power deal. It gives Vistra a right of first refusal, from April 2028, on any future on-site generation or power build-out at New Era’s Ector County site, and a five-year right of first offer on power and battery projects New Era pursues elsewhere. It also makes New Era pay Vistra back for substation and transmission work. Once power flows, New Era must issue Vistra non-voting equity equal to 5% of the fully diluted equity of the project company that owns the powered part of the data centre.
A plain comparison helps. Think of a landlord who takes a share of a restaurant’s profits on top of the rent. The rent (the power price) covers the landlord’s costs; the profit share pays off only if the restaurant does well. Vistra’s nuclear deals with Amazon and Meta are pure rent: fixed volumes at fixed prices from hyperscalers with investment-grade balance sheets. FinanceFeeds’ breakdown of those 3,809 MW of nuclear contracts shows none of them carries an equity component. The customer’s credit was the collateral. New Era has no such credit, so Vistra asked for collateral and an upside share instead: a claim on the tenant lease revenue the data centre earns, not just the meter.
New Era’s chief executive described the deal in exactly these terms. “Having contracted power for Phase 1 in New Era’s name is an incredible milestone which we believe materially reduces Phase 1 development risk at TCDC,” said Charlie Nelson, Chairman and Chief Executive Officer of New Era Energy & Digital. “We believe aligning our interests will expedite development timelines and give potential tenants confidence in our project.”
Quick Take: The megawatts are small. What matters is the structure: fixed-price supply plus a 5% equity option and first call on expansion, backed by up to $198.8 million of collateral. Vistra is getting paid like a lender with a stake in the upside, not just like a utility selling power.
How Vistra and the Market Responded
Vistra’s own disclosure was minimal. The company filed no 8-K on the deal. Its most recent current report on EDGAR is its 7 August earnings release, so management evidently judged a 207 MW contract immaterial for a company guiding to $6.8 billion to $7.6 billion of 2026 adjusted EBITDA. Its only public comment came in New Era’s release, from its head of corporate development.
The market treated the deal the same way. On 21 September New Era closed at $7.65, up 30.5% from $5.86, on 25.5 million shares, about four times its 6.4 million average volume according to Nasdaq data. That added roughly $190 million to a company worth $804.5 million at the close. Vistra rose 11 cents. Vistra’s shares are still around 36% below their 52-week high of $219.82, a gap FinanceFeeds traced to the company’s hedge book in its Vistra $225 bull / $95 bear stock prediction. This deal does not change that picture.
The deal does fit a pattern in how Vistra is positioning. In June 2026 it became a founding investor in KKR Helix C L.P., committing up to $1 billion, with $500 million upfront and $500 million more tied to “commercial power supply milestones for our existing generation assets”, according to Vistra’s second-quarter 10-Q. The fund targets “hyperscale data center development and operations” alongside generation and transmission. Helix is Vistra taking fund-level equity in AI infrastructure. The New Era stake is the same idea at the level of a single project, sized at one site’s first phase.
The same 10-Q says Vistra “continue[s] to engage in discussions with various counterparties regarding the potential long-term sale of power from our generation facilities”. Selling to hyperscalers and sharing in developer upside are now two separate channels for that pitch. Contrast Bloom Energy’s Brookfield-financed model, where the financier owns the asset and the vendor takes no equity.
Vistra kept its public comment short. “Demand for reliable power to support digital infrastructure continues to grow across the United States,” said Claudia Morrow, Senior Vice President of Corporate Development and Strategy at Vistra. “We are pleased to work with New Era on a long-term power arrangement for the TCDC project and to establish a framework that allows us to evaluate additional power opportunities together over time.”
The Numbers: Cheap West Texas Power, and a Counterparty That Must Raise Money
Two data sets explain the deal better than either press release. The first is Vistra’s own price table. In the second quarter of 2026 Permian Basin gas averaged minus $3.10 per MMBtu, meaning producers paid to have it taken away, against plus $1.10 a year earlier. ERCOT West Hub power averaged $24.71 per MWh, the second-lowest of the nine hubs in Vistra’s table and 18% below ERCOT North Hub’s $30.20. The Odessa plant sits in the part of Vistra’s footprint where fuel is almost free but power is also cheap, because pipelines and transmission lines out of the Permian are full. A 20-year contract with load built right next to the plant takes that plant’s output away from the weakest price point in Texas. The contract price was not disclosed. For scale, 207 MW running every hour of the year is about 1.81 TWh. At Q2’s West Hub average that would be worth about $45 million a year, roughly 0.6% of Vistra’s 2026 EBITDA guidance midpoint. That is immaterial for Vistra and existential for New Era.
The second data set is New Era’s balance sheet, and this is where the deal is tighter than the share price suggests. At 30 June 2026 New Era had $69.8 million of cash, $15 million of restricted cash and $174.7 million of total assets, most of it $80.4 million of land. Second-quarter revenue, from legacy oil and gas wells, was $36,497, against $16.1 million of general and administrative expense. It lost $31.3 million in the first half. As recently as its first-quarter report it disclosed “substantial doubt” about continuing as a going concern, a doubt it said April’s financings resolved.
Against that, the power deal requires a $116 million letter of credit within 15 business days of the 18 September signing, which by our count is 9 October, plus up to $82.8 million more by first delivery. That is up to $198.8 million of collateral, 2.85 times New Era’s June cash and 1.14 times its total assets. Its $290 million Macquarie term loan has only $20 million committed; the remaining $270 million is “available solely at Macquarie’s discretion”, according to the 10-Q. The 30% share price jump makes an equity raise easier, and that may be exactly what it is for.
| Term | Vistra–Amazon / Meta (nuclear) | Vistra–New Era (gas) |
|---|---|---|
| Capacity | Up to 1,200 MW (AWS) + 2,609 MW (Meta) | 200–207 MW |
| Term | 20 years | 20 years + annual renewals |
| Counterparty credit | Investment-grade hyperscalers | Pre-revenue developer, $69.8m cash |
| Collateral | None disclosed | $116m LC + up to $82.8m |
| Equity to Vistra | None | 5% non-voting of powered project |
| Expansion rights | Uprates at Vistra’s own plants | ROFR on on-site builds from April 2028; 5-year ROFO |
| Pros for Vistra | Certain cash flow, strong credit | Collateralised, free upside, first call on growth |
| Cons for Vistra | No upside beyond contract price | Project may never reach delivery; equity is illiquid |
That comparison is why the deal suits Vistra even though it is small. FinanceFeeds’ Vistra-versus-Micron analysis showed the market has already pulled back the AI-power multiple it briefly gave Vistra in 2025. Vistra’s 10-Q shows Texas gas generation only 69% hedged for 2027, against 100% for its Texas nuclear and coal. Locking in 20 years of West Texas gas output from 2027 fills the least-hedged part of the book.
Quick Take: For Vistra this is a hedge on its cheapest, least-contracted Texas gas output, worth maybe 0.6% of EBITDA. For New Era it is a collateral bill larger than its balance sheet, due in weeks.
The Texas Politics: The Same Day, Abbott Tightened the Moratorium
Timing makes this deal harder to read than the release suggests. On 21 September, the day New Era announced the contract, Governor Greg Abbott ordered the Texas Commission on Environmental Quality to stop issuing permits for data centres until ERCOT and the Texas Water Development Board complete their audits, the Texas Tribune reported. “Simply put, Texans must come first,” Abbott wrote. “Data centers must pay their own way, protect our grid and water and complete the ERCOT and TWDB audits. Until they do, TCEQ will issue no permits sought by data center projects.”
The Tribune reported that the new order appears to target developers who build “behind the meter”, generating their own power to avoid grid approval. It extends the 3 August directive under which, the Tribune noted, projects that fail a “comprehensive verification and audit” are to be denied a grid connection; Houston Public Media reported that new data centres cannot join the ERCOT grid until regulators complete it. ERCOT is weighing 474 GW of large-load requests, more than five times the state’s record peak demand.
New Era’s release says TCDC already has “construction permits in hand”. But the power deal itself touches the grid. Power can come “from other available sources or the ERCOT grid”, and at more than 75 MW the load falls under Senate Bill 6’s large-load interconnection standards. The PUCT’s draft rule, published on 12 March 2026, would require financial security of $50,000 per MW before an interconnection study and a non-refundable fee of the same amount, according to Greenberg Traurig. At 207 MW, that would be another roughly $10 million of security on top of Vistra’s letter of credit. SB6 also requires large loads connected after 2025 to accept ERCOT curtailment in emergencies.
Federal policy is moving in the same direction. As FinanceFeeds reported, the House passed the Ratepayer Protection Act by 417 votes to 3, which would ask state commissions to make data centres above 100 MW cover the full incremental cost of the grid built for them. The Vistra–New Era framework already works this way: New Era pays for the substation and transmission lines and posts collateral before Vistra builds. That is why the deal holds up under this kind of scrutiny. Abbott’s position has changed within a year. A year ago he backed Vistra’s Permian expansion, saying “Vistra’s bold investment in the Permian Basin will reinforce our state’s electric grid, spur jobs, and drive regional economic growth for years to come”, as quoted in Vistra’s September 2025 announcement. Generation is still welcome in Texas; data centres now have to prove they pay their own way.
What Happens Next: Three Predictions
1. New Era raises equity before 9 October. A $116 million letter of credit against $69.8 million of June cash leaves little choice. The bank issuing the letter will want cash collateral or a guarantor, and the Macquarie tranches above $20 million depend on the lender’s approval. With the stock up 30% and an S-3 shelf already effective since May, an at-the-market or overnight offering is the most likely route. If New Era misses the posting date, the PPA’s default and termination provisions give Vistra remedies, and the market will learn more from that deadline than from Monday’s price move.
2. Vistra repeats the equity structure with other developers, not hyperscalers. Hyperscalers will not give up equity in their own campuses. Developers without investment-grade credit have to offer something. Expect the 5% stake plus right-of-first-refusal package to appear again at Vistra’s Texas gas sites over the next 12 months, especially at the Permian Basin plant near Monahans, where Vistra is adding 860 MW for a site total of 1,185 MW, financed in part by a $583 million, 3.0% Texas Energy Fund loan signed in June 2026. The KKR Helix commitment gives Vistra a second route into the same assets.
3. Texas decides the timeline, not Vistra. Delivery is scheduled for Q3 2027, but conditions precedent run to December 2027 and the state audits have no fixed end date. Fermi’s Project Matador in the Panhandle shows how a well-publicised Texas campus can still slip when permits and tenants arrive out of order. If ERCOT’s audit delays interconnection for any grid-sourced portion, first power is more likely in 2028 than in 2027.
For brokers and platforms pricing AI-power names, the conclusion is to value this deal by its structure, not its size. Vistra has found a way to sell power to weaker-credit developers without taking their credit risk, and New Era’s next funding round will be the first test of whether that model works.
Frequently Asked Questions
What did Vistra agree with New Era Energy & Digital?
Vistra’s affiliate Luminant signed a 20-year agreement to supply 200 to 207 MW from Vistra’s 1,180 MW Odessa gas plant to New Era’s Texas Critical Data Center, starting in Q3 2027. A separate framework gives Vistra 5% non-voting equity in the powered project once delivery begins, plus rights of first refusal and first offer on future power projects.
Is the New Era deal material to Vistra’s earnings?
No. Vistra filed no 8-K on the deal and its shares rose only 0.08%. At the Q2 2026 ERCOT West Hub average of $24.71 per MWh, 207 MW running all year would be worth about $45 million annually, roughly 0.6% of the midpoint of Vistra’s $6.8 to $7.6 billion 2026 adjusted EBITDA guidance. The contract price was not disclosed.
Why does Vistra get a 5% stake in the data centre?
New Era lacks the investment-grade credit of Amazon or Meta, so Vistra asked for collateral and upside instead. The 5% non-voting stake in the powered project company gives Vistra a share of tenant lease revenue if the data centre succeeds, while a $116 million letter of credit protects it if the project stalls.
Can New Era afford the Vistra power contract?
Not from existing cash. New Era must post a $116 million letter of credit and up to $82.8 million more, up to $198.8 million in total, against $69.8 million of cash and $174.7 million of total assets at 30 June 2026. It will likely need new equity or discretionary draws from its $290 million Macquarie facility.
Does Governor Abbott’s data centre moratorium affect the Vistra deal?
Possibly. On 21 September Abbott told TCEQ to stop issuing new data centre permits pending ERCOT and water audits. New Era says it already holds construction permits, but any power drawn from the ERCOT grid for a load above 75 MW falls under SB6 interconnection rules and the 3 August audit, which could delay the 2027 start.
How does this compare with Vistra’s nuclear deals with Amazon and Meta?
Those contracts cover 3,809 MW of nuclear power over 20 years with investment-grade hyperscalers and include no equity component. The New Era deal is about 5% of that size, uses gas rather than nuclear power, and, unlike them, comes with an ownership stake in the customer’s project.