Updated 18 September 2026. Brent crude: $102.41 a barrel, down $2.41 (-2.30%) on the day. WTI: $100.04, down $1.87 (-1.84%). Both benchmarks are lower for a third straight session after Saudi Arabia signalled it will restore roughly half the capacity of its damaged East-West pipeline within days and the full line within about six weeks.
Verdict: the supply-shock premium is draining, not gone. Brent has given back more than $5 from its 14 September highs near $108, but it is still trading roughly $12 above the $90 that the US Energy Information Administration pencils in for the second half of 2026. The next move belongs to the pumping station, not to the Fed.
Prices are spot quotes from Trading Economics as of 18 September 2026 and cross-checked against Investing.com’s front-month Brent contract ($102.50, -2.21%, previous close $104.82).
Key facts
- Brent is at $102.41, a third consecutive decline. Investing.com’s front-month contract shows the same move at $102.50, against a previous close of $104.82.
- WTI has slipped back to the $100 handle at $100.04, down 1.84%.
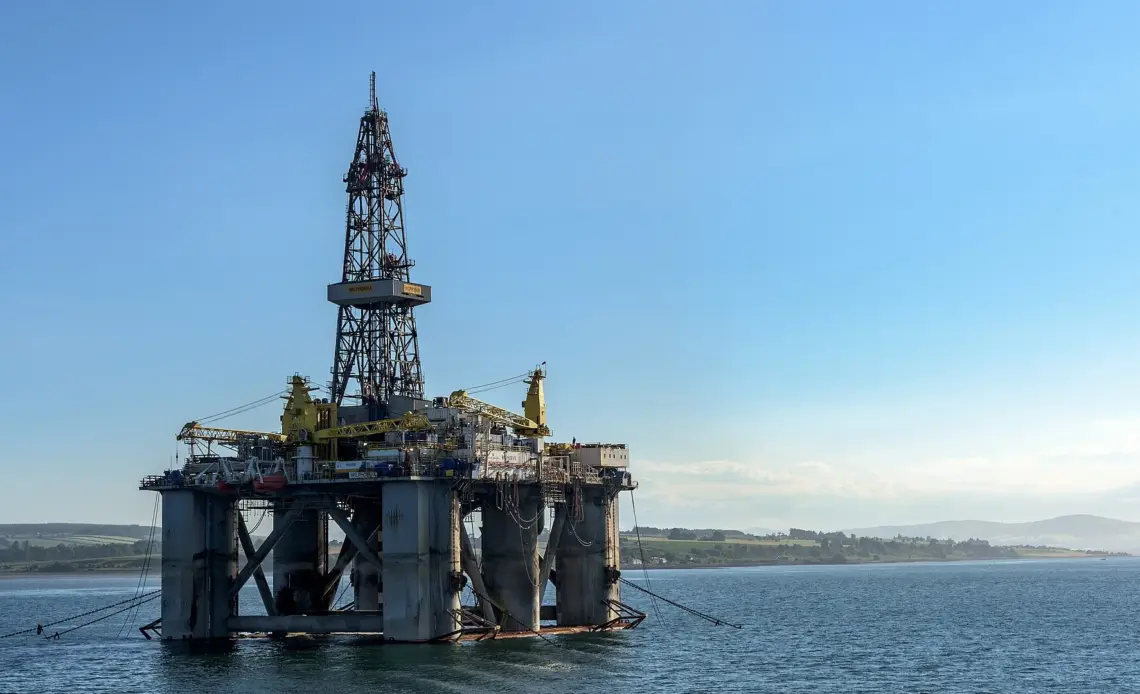
- The trigger is the pipeline, not demand. Saudi Arabia is working to bring back about half of the East-West pipeline’s capacity within days, with full restoration targeted inside roughly six weeks. The line, which carries crude to the Red Sea coast and lets exports bypass the Strait of Hormuz, was damaged by drone strikes last week.
- Washington is talking the outage down. US Energy Secretary Chris Wright told CNBC on 15 September that the disruption is a “brief and temporary interruption” that “will be measured in days.”
- Independent analysts are less relaxed. Satellite imagery showing significant damage to a pumping station has led some analysts to argue the line could stay impaired for weeks rather than days.
- Riyadh is not waiting. Saudi Arabia has been rerouting barrels through the Strait of Hormuz using shuttle vessels and ship-to-ship transfers, which restores volume but reinstates exactly the chokepoint exposure the pipeline exists to avoid.
- Geopolitics is still live. President Trump has said he is weighing a resumption of strikes on Iran ahead of a Gulf leaders meeting in New York next week.
Why Brent is falling while the pipeline is still broken
The market is not pricing the outage. It is pricing the duration of the outage, and that estimate has been revised down twice in three sessions.
When the drone strikes landed last week, Brent ran toward $108 and the $120 scenario re-entered analyst notes. That rally assumed a multi-week loss of the alternative route around Hormuz, at a moment when Hormuz itself was the subject of Iranian threats. Two things have since undercut it. First, Saudi Aramco began moving barrels by sea instead, so physical export volumes did not fall as far as the headline suggested. Second, the restoration timeline shortened: half capacity in days, full capacity in about six weeks. That is a different market from the one that greeted the initial outage on 16 September, when the supply loss still looked open-ended.
That is why the decline has been orderly rather than violent. Brent settled at $105.83 after the first restart reports, printed a $104.82 close, and has now worked down to $102.41. Each session has removed a slice of risk premium rather than repricing the whole event.
The risk that remains is asymmetric in an unusual way. A pipeline that is half-restored is not half as risky, because the half that is running through Hormuz on shuttle tankers is the half that is exposed if the Iran situation deteriorates. The two catalysts are linked, and the market is currently treating them as separate.
What the Fed hike has to do with the oil price
On 16 September the Federal Open Market Committee raised the federal funds rate by a quarter point to 3.75%-4.00% in a unanimous vote, the first increase since 2023, and lifted its median projection for end-2026 rates to 4.1% from 3.8%.
That matters to crude in two directions and they partly cancel. A higher policy path is dollar-positive, and a firmer dollar mechanically weighs on dollar-denominated barrels. But the reason the Fed moved is energy-driven inflation, which is to say the oil price is currently an input to the rate path rather than only a victim of it. A sustained retreat toward $90 Brent would take pressure off the October and December decisions; a re-test of $108 would do the opposite, and would sharpen the stagflation question now being asked of the US economy.
For the moment the causation is running from oil to rates, not the other way around. Falling crude on 17 and 18 September pulled Treasury yields back from their post-decision spike, which is also why gold and silver rallied on the same two sessions.
Scenarios for Brent into Q4 2026
Anchors below are named forecasts, not price targets of our own. Spot at the time of writing is $102.41.
| Scenario | Brent range | What has to happen | Anchor |
|---|---|---|---|
| Bear | $88 – $92 | The East-West line comes back on the announced timetable, shuttle-tanker rerouting proves durable, and the Iran file cools ahead of the New York meeting. Risk premium unwinds to roughly where it sat before the drone strikes. | The EIA’s Short-Term Energy Outlook puts Brent averaging around $90 a barrel in the second half of 2026, itself $8 higher than its previous month’s estimate. |
| Base | $98 – $106 | Half capacity returns on schedule but the remainder slips past the six-week guide, and Hormuz headline risk keeps a premium of several dollars embedded. Brent chops in the range it has held since the strikes. | Where the market is trading now, with Brent at $102.41 and WTI at $100.04. |
| Bull | $115 – $120 | Repairs slip materially, or strikes resume against Iran and the shuttle-tanker workaround through Hormuz becomes untenable. This is the scenario that put $120 back into analyst notes on 14 September. | Sell-side commentary during the 14 September spike, when Brent neared $108 and $120 was described as back on the table. |
Note the tension in the sell-side base case. Goldman Sachs’s published Q4 2026 Brent forecast has been $80, and JPMorgan’s has been $80 for Q4 and $86 for Q3, both set in July before the pipeline was hit. Those numbers sit below even the bear column above. The gap between a $80 modelled Q4 and a $102 spot is the entire live geopolitical premium, and it is the single number to watch as the repair proceeds.
Quick take
The trade is about repair speed, not about barrels. Saudi Arabia is not short of crude; it is short of a route that avoids Hormuz. Every day the East-West line stays down, more Saudi volume moves through the chokepoint on shuttle tankers, which lowers the supply-loss premium and raises the chokepoint premium at the same time.
Three things would change the picture. A confirmed restart of half the line (bearish, and largely priced). A repair timeline slipping past six weeks (bullish, not priced). Renewed US strikes on Iran before or during the Gulf leaders meeting in New York next week (sharply bullish, and the reason a $115-$120 column still belongs on the table).
Watch the $100 level on WTI. It closed above $100 for the first stretch of this episode and is now sitting on it. A clean break below would signal that traders have stopped pricing the pipeline as a supply event at all.
FAQ
What is the Brent crude price today?
Brent is trading at $102.41 a barrel on 18 September 2026, down $2.41 or 2.30% on the day, per Trading Economics. Investing.com’s front-month contract shows $102.50, down 2.21% from a previous close of $104.82.
Why is the oil price falling if the Saudi pipeline is still damaged?
Because the expected length of the outage has shortened. Saudi Arabia has signalled it can restore roughly half the East-West pipeline’s capacity within days and the full line within about six weeks, and in the meantime it is moving barrels by sea. The market is repricing duration, not supply.
What is the East-West pipeline and why does it matter?
It carries Saudi crude from the eastern oil fields across the country to the Red Sea coast, allowing exports to reach buyers without passing through the Strait of Hormuz. When it is down, more Saudi barrels must transit Hormuz, which is the chokepoint Iran has repeatedly threatened.
How high could Brent go if repairs slip?
The $115-$120 band is the range analysts were describing during the 14 September spike, when Brent neared $108. Reaching it would most likely require a repair delay beyond the six-week guide combined with renewed escalation against Iran, not one or the other alone.
What is WTI trading at?
WTI is at $100.04 a barrel on 18 September 2026, down $1.87 or 1.84%, holding just above the $100 level.
Do bank forecasts support these prices?
Not at current levels. Goldman Sachs’s Q4 2026 Brent forecast has been $80 a barrel and JPMorgan’s $80 for Q4, both set in July. The EIA’s more recent Short-Term Energy Outlook has Brent averaging around $90 in the second half of 2026. Spot is well above all three, which is the measure of how much geopolitical premium is currently embedded.
Does the Fed’s rate hike push oil lower?
Indirectly and modestly. The 16 September quarter-point hike to 3.75%-4.00% supports the dollar, which is a headwind for dollar-priced crude. But the Fed moved largely because of energy-led inflation, so for now the oil price is driving the rate path more than the rate path is driving oil.
Sources
Spot prices: Trading Economics (Brent, WTI), 18 September 2026; Investing.com front-month Brent, 18 September 2026. Pipeline restart timeline and Chris Wright quote: CNBC, 15-16 September 2026. Analyst forecasts: Goldman Sachs and JPMorgan Q4 2026 Brent forecasts as published in July 2026; US Energy Information Administration Short-Term Energy Outlook.
Disclaimer: This article is for informational purposes only and does not constitute financial, investment or trading advice. Commodity prices are volatile and past performance is not indicative of future results. FinanceFeeds does not recommend buying or selling any asset. Always do your own research and consider consulting a licensed financial adviser before making investment decisions.